Crypto loans
Also called: Loans, Crypto-backed loans, Collateralized crypto loans, Crypto borrowing
Definition. A crypto loan lets you borrow stablecoins or fiat against crypto you lock as collateral, with no credit check. You borrow less than the collateral is worth, and it is sold if the loan-to-value ratio reaches the liquidation threshold.
Stanislav Vovchyk · Updated Nov 7, 2026 · 13 tools have it
In short
- Max LTV is what you can borrow; the liquidation threshold is where collateral is sold. The gap is your buffer.
- In DeFi, any wallet can liquidate you once the health factor drops below 1, often with no warning.
- Liquidation costs more than the debt: Coinbase lists a 4.38% penalty on top.
- MiCA does not regulate crypto lending, and in the US a liquidation is a taxable disposal.
A crypto loan is a loan where you lock crypto as collateral and borrow stablecoins or fiat against it, with no credit check. You borrow less than the collateral is worth (over-collateralisation) and pay interest at a variable or fixed rate. If the loan-to-value ratio (LTV) reaches the lender's liquidation threshold, some or all of the collateral is sold to repay the debt.
What is a crypto loan?
A crypto loan is secured credit where crypto is the only security, so the lender looks at your collateral's price, not your income. Three kinds of provider offer them: centralised (CeFi) lenders and exchanges, which hold your collateral themselves; exchanges that sit in front of DeFi; and DeFi protocols such as Aave, Morpho and Sky, which keep the collateral in a smart contract.
Coinbase is the main example of the middle kind. It converts your BTC 1:1 into cbBTC and posts it to Morpho on Base.
Sky (formerly MakerDAO) vaults work slightly differently. You lock ETH and the protocol mints DAI or USDS for you, charging a stability fee as the interest, so nothing is lent out of a depositor pool.
All 14 services in our catalogue that list crypto loans are exchanges, and BitMart, MEXC, BingX and XT.COM list their loans under earn products. Check which side of the trade a product puts you on: as a borrower you post collateral, while in an earn product you are the lender.
Margin or futures trading uses the same LTV and liquidation logic, but you borrow to raise your exposure on an exchange. A crypto-backed loan pays out stablecoins or fiat you can spend. Flash loans are a separate DeFi tool with no collateral: they are borrowed and repaid inside one blockchain transaction, or the whole transaction reverses. Developers and arbitrageurs use them. Consumers looking for cash don't.
How a crypto loan works, step by step
- Liquidity is supplied. In DeFi, depositors put stablecoins or crypto into a pool. In CeFi, the money comes from the lender's balance sheet or credit lines.
- You lock collateral, for example BTC (wrapped as cbBTC on Coinbase/Morpho) or ETH. A custodian or a smart contract holds it.
- The loan is paid out in USDC, another stablecoin or fiat, up to the maximum LTV (for example 75%). Interest starts to accrue, at a variable or fixed rate.
- An oracle reports prices. Each update recalculates your LTV or health factor.
- Warning, or no warning. A CeFi lender usually sends a margin call at an LTV between the maximum and the liquidation level. In DeFi there is usually no notice, only the health factor on the dashboard.
- You act. Add collateral or repay part of the loan to bring the LTV down, or repay in full to unlock the collateral.
- Liquidation. If the LTV reaches the liquidation threshold (health factor below 1), a liquidator repays part or all of the debt. In CeFi that is the platform's own desk. In DeFi it is any third-party bot.
- Collateral goes to the liquidator. The liquidator receives collateral worth the repaid debt plus a bonus or penalty of about 4 to 5%. Whatever is left stays with you.
- Lenders are paid. Liquidity suppliers earn interest. If the collateral did not cover the debt (bad debt), the loss can be passed on to them.
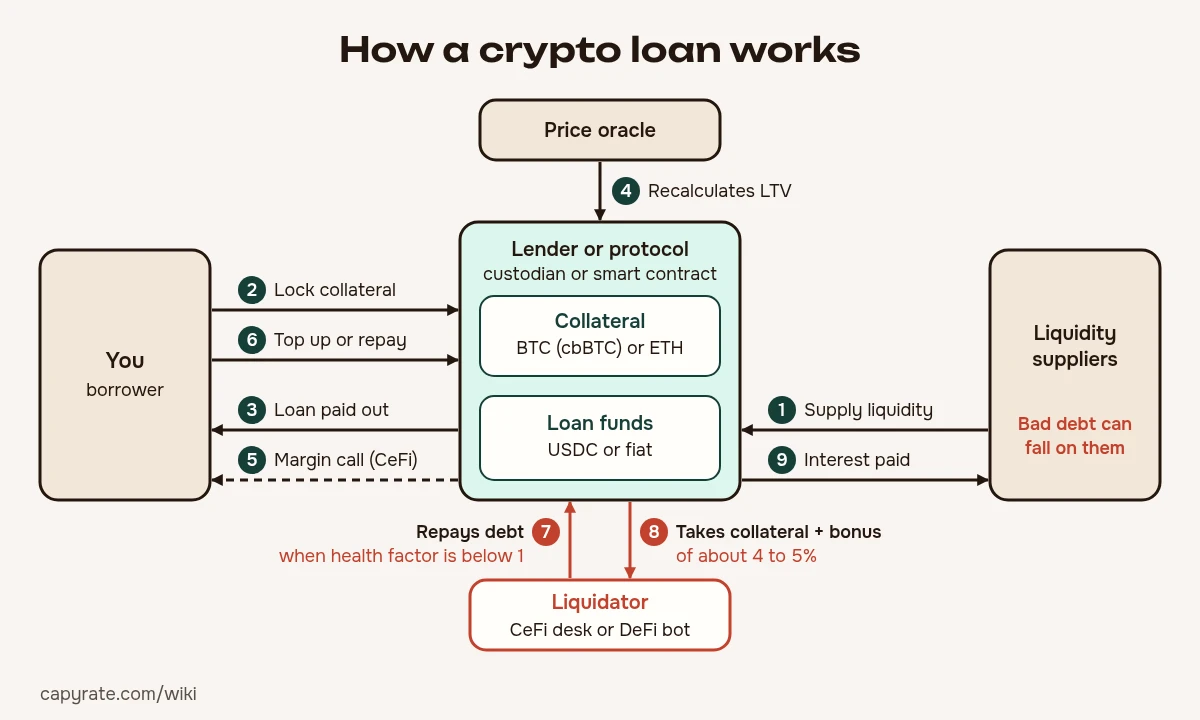 The nine steps of a crypto loan, from supplied liquidity to liquidation and interest paid to lenders.
LTV, liquidation threshold and health factor: the numbers that matter
LTV = loan balance (including accrued interest) ÷ market value of collateral. Coinbase uses this definition.
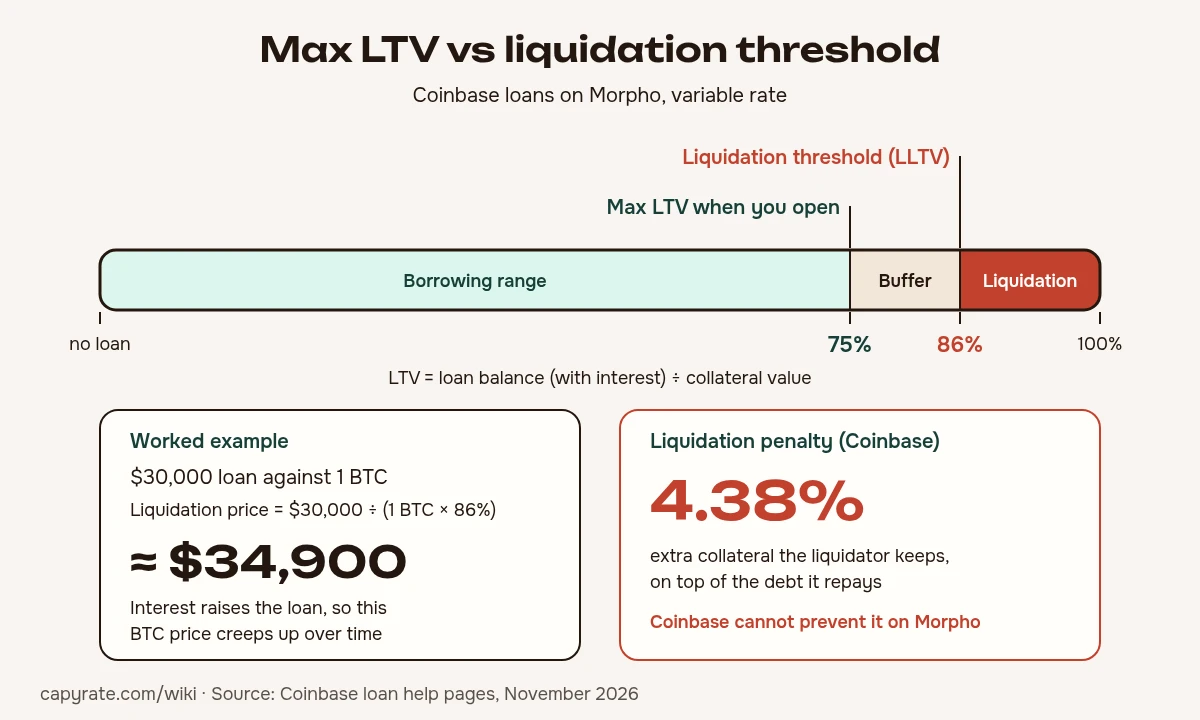 The gap between the 75% max LTV and the 86% liquidation threshold is your safety buffer.
Max LTV is the most you can borrow when you open the loan. The liquidation threshold (Morpho calls it LLTV, liquidation loan-to-value) is the LTV at which your collateral gets sold. The gap between the two is your safety buffer.
On Coinbase's Morpho loans the variable-rate maximum is reported as 75% and the LLTV is 86%. Coinbase allows partial collateral withdrawals while LTV stays below 86%.
Liquidation price = loan balance ÷ (collateral units × liquidation LTV).
Worked example: a $30,000 loan against 1 BTC with an 86% LLTV is liquidated when BTC falls to about $34,900. Accrued interest raises the loan balance, so the liquidation price creeps up over time. I'd open a loan well below the maximum LTV, not at it, so that a normal price swing doesn't reach the threshold.
Aave health factor = (total collateral value × weighted average liquidation threshold) ÷ total borrow value. Aave Governance sets the threshold for each collateral asset, and Aave's own help example uses 80%. Aave's liquidation rules:
- A position can be liquidated once its health factor drops below 1.
- Up to 50% of the debt can be liquidated at once while the health factor is above 0.95 and both collateral and debt are at least $2,000.
- Up to 100% can be liquidated when the health factor is at or below 0.95, or when collateral or debt is below $2,000.
- A partial liquidation must leave at least $1,000 of both collateral and debt.
Aave's newer documentation describes a Dutch-auction bonus: the lower your health factor falls, the bigger the liquidator's bonus. Aave's E-Mode allows a higher LTV when the collateral and the borrowed asset are correlated, for example USD stablecoins borrowed against USD stablecoins. Aave V3.7 removed Isolation Mode and debt ceilings and replaced them with isolated E-Mode categories.
Morpho treats a position as liquidatable once its LTV is above the market's LLTV. Put another way, its health factor (collateral value × LLTV ÷ amount borrowed) has fallen below 1. Its liquidation incentive factor is LIF = min(1.15, 1/(0.3 × LLTV + 0.7)), which works out to a bonus of about 4 to 5% at an 86% LLTV, in line with the 4.38% penalty Coinbase lists. The liquidator keeps the whole bonus and Morpho takes no fee, so a liquidation costs you more collateral than the debt it clears.
Variable rates can move fast. Aave V3 sets rates by utilisation using two slopes. Once a pool is used beyond its optimal point, the rate climbs along a much steeper second slope.
CeFi vs DeFi crypto loans (and crypto loans vs Earn accounts)
| CeFi loan (lender or exchange) | DeFi loan (Aave, Morpho, Sky) | Earn / interest account | |
|---|---|---|---|
| Your role | Borrower | Borrower | Lender |
| Who holds the coins | The platform or its custodian | A smart contract, visible on-chain | The platform |
| KYC | Yes | Usually none at protocol level; a front end such as Coinbase adds it | Yes |
| Who liquidates | The platform's desk | Anyone (permissionless bots) | Not applicable |
| Warning before a sale | Usually a margin call | Usually none: the health factor is all you get | Not applicable |
| Can your coins be re-lent | Depends on the terms (rehypothecation) | Set by the contract rules, visible on-chain | Often yes: that is how the yield is paid |
| Main failure mode | Lender bankruptcy or frozen withdrawals | Smart-contract bugs, bad oracle prices, bad debt | Platform bankruptcy, leaving you an unsecured creditor |
| If collateral falls short | Set by the loan agreement | Can be passed to lenders (Morpho Vaults V2 lowers the receipt token's value) | Losses can fall on depositors |
Most of the 2022 losses came from the right-hand column. Celsius Earn, BlockFi Interest Accounts, Gemini Earn (run with Genesis) and Nexo's Earn Interest Product were all lending programmes, and US regulators treated several of them as unregistered securities.
Risks: what went wrong in 2022 and what can still go wrong
The 2022 failures
- BlockFi. On February 14, 2022, BlockFi settled with the SEC and 32 states for $100M: a $50M SEC penalty plus $50M to the states. The SEC found its interest accounts were unregistered securities and that it had misrepresented the risk of its loan portfolio. BlockFi filed for Chapter 11 on November 28, 2022, citing FTX exposure, and a court filing names Three Arrows Capital as one of its largest borrowers.
- Celsius. Celsius froze withdrawals on June 12 and 13, 2022, and filed for Chapter 11 on July 13. The FTC alleged it marketed itself as safer than banks, claimed "no risk" profits from secured loans, said it made no unsecured loans and advertised yields of up to 18% APY. In July 2023 it agreed to a $4.7B judgment, suspended so assets could go back to consumers. On July 20, 2026, its founders were ordered to pay $16.5M in total.
- Voyager filed for bankruptcy after Three Arrows Capital defaulted on more than $650M.
- Genesis halted Gemini Earn withdrawals in November 2022 while holding about $900M for about 340,000 investors, and paid a $21M SEC penalty on March 19, 2024. Nexo paid $45M to the SEC and states on January 19, 2023, over its Earn Interest Product.
The title lesson. On January 4, 2023, the Celsius bankruptcy court ruled that the terms of use had passed title to Earn deposits to Celsius, which made more than $4.2B of assets from over 600,000 users property of the estate. The court expressly did not decide who owned Borrow Program collateral. Your contract decides whether you get your coins back, not where they physically sit.
Risks that remain
- No grace period. DeFi liquidation is instant and permissionless. Coinbase says it cannot prevent liquidation on Morpho, and its optional loan-protection feature may fail in volatile markets.
- Liquidation cascades. In sharp falls, forced sales push prices lower and trigger more liquidations. On Aave a partial liquidation can turn into a full one once the health factor reaches 0.95.
- Oracle risk. A wrong or delayed price feed can trigger a liquidation, or block one that should happen.
- Bad debt. If collateral sells for less than the debt, lenders in the pool take the loss.
- Stablecoin depeg. You owe the stablecoin you borrowed. If it loses its dollar peg, your debt and your proceeds can move against you.
Taxes and regulation by country
| Jurisdiction | Tax or regulatory status | Key dates |
|---|---|---|
| United States | Crypto is property for tax purposes. Taking the loan is generally not treated as a sale, though no IRS FAQ addresses crypto loans directly. A liquidation transfers ownership, so it is a disposal and can create a capital gain or loss even if you never receive cash. | Form 1099-DA: brokers report gross proceeds from Jan 1, 2025, and basis for certain transactions from Jan 1, 2026 |
| European Union | MiCA Recital 94 leaves crypto lending and borrowing to national law. Licensed providers (CASPs) can still offer it under MiCA's general conduct rules: they must disclose counterparty risk, collateral shortfall and loss of access, and need prior express and specific consent to use client assets. MiCA safeguarding does not cover assets used in lending. | MiCA adopted 2023. An EBA/ESMA report of Jan 16, 2025 found crypto lending in at least 16 member states. ESMA Q&A 2883 issued June 18, 2026. Sept 2026: EBA asked the Commission to consider bringing lending into MiCA |
| United Kingdom | The FCA proposes allowing retail crypto borrowing with mandatory over-collateralisation, modelled LTV, margin-call and liquidation levels, clear disclosures and express consent for each engagement. Proprietary tokens could not be used as collateral or incentives. The FCA dropped creditworthiness and forbearance requirements, which the Financial Services Consumer Panel criticised. | CP25/40 published Dec 16, 2025. CP26/4 (treatment of retail borrowing collateral) published Jan 23, 2026 |
The IRS digital assets page sets out what counts as a disposal. Moving coins between your own wallets generally does not count. In the EU, ESMA Q&A 2883 confirms that a MiCA-licensed provider's safeguarding rules do not protect crypto you have lent or pledged.
How to check a crypto loan yourself
- Work out your liquidation price with the formula above before you borrow. Rerun it as interest accrues or when you add collateral.
- Find three numbers in the help centre or loan agreement: the liquidation LTV, the margin-call LTV and the liquidation penalty. Get all three before you borrow.
- For DeFi loans, check the health factor on the protocol's app or a block explorer. Below 1.0, anyone can liquidate the position. Also check which oracle prices the market.
- For Coinbase/Morpho loans, confirm the collateral is on-chain as cbBTC or cbETH by looking up your address or position on the Morpho app or Basescan.
- Search the terms for "title", "rehypothecation", "lend", "pledge" and "use of collateral". If title passes to the lender, or it can re-lend your coins, you are an unsecured creditor if it fails.
- Verify the licence. In the US, look up the lender's NMLS ID on nmlsconsumeraccess.org and confirm your state is covered. In the UK, search the FCA Register. In the EU, check ESMA's interim MiCA CASP register, keeping in mind that lending itself is outside MiCA.
- Keep records of the loan date, your collateral's cost basis and any liquidations. US liquidations should appear on Form 1099-DA.
How to choose a crypto lender
- Rate: the APR, and whether it is fixed or variable. Coinbase added fixed-rate, fixed-term USDC loans against BTC on September 22 to 23, 2026, through Morpho Midnight. At that point its variable-rate loans had more than $1.4B active against nearly $3B of collateral.
- Buffer: the gap between max LTV and liquidation LTV.
- Penalty: what a liquidation costs on top of the debt.
- Margin calls: whether you get one, at what LTV, and through which channel.
- Custody: segregated or on-chain, with an explicit statement that collateral is not rehypothecated. A lender's proof of reserves is extra evidence, not a guarantee.
- Collateral and limits: Coinbase launched in January 2025 with BTC only, a $100,000 cap and a 133% minimum collateral ratio. Reported collateral now includes BTC, ETH (up to $1M), SOL, XRP, DOGE, ADA and LTC.
- Availability: Coinbase's loans are reported as available to US customers except in New York.
- Licensing, repayment and fees: a registration you can look up, early repayment terms, and origination or withdrawal fees.
The services that offer crypto loans are listed below this entry.
Tools that have it
From the directory, based on each tool's own feature list. Check the plan: some offer it only on paid tiers or certain apps.
- B
 BybitOffers crypto loans against collateral · Paid
- B
 BinanceBinance Loans lets users borrow against crypto · Paid
- O
 OKXOffers crypto loans on the exchange · Paid
- K
 KuCoinOffers crypto lending and borrowing · Paid
- M
 MEXCLoans listed among earn products · Paid
- B
 BitfinexBitfinex Borrow against crypto collateral · Free
- G
 GateCrypto loans with published interest · Paid
- B
 BitMartCrypto loans listed under earn products · Paid
- B
 BingXCrypto loans listed under earn products · Paid
- X
 XT.COMEarn and Loan products listed · Paid
- H
 HTXOffers crypto loans on the exchange · Paid
- C
 Crypto.comOffers crypto-backed loans · Paid
- B
 BitgetOffers crypto loans on the exchange · Paid
FAQ
Do crypto loans need a credit check?
Usually not. The loan is over-collateralised, so the lender relies on the value of your crypto rather than your income or credit history. CeFi lenders and front ends such as Coinbase still require KYC identity checks.
Is taking out a crypto loan taxable in the US?
Taking out the loan is generally not treated as a sale, although no IRS FAQ addresses crypto loans directly. A liquidation is a disposal of your collateral and can create a capital gain or loss.
Can I borrow against bitcoin on Coinbase, and in which states?
Yes. Coinbase offers USDC loans against BTC through Morpho on Base, with variable rates and, since September 2026, fixed rates. The loans are reported as available to US customers in every state except New York.
What is rehypothecation in crypto lending?
It means the lender re-uses or re-lends the collateral you posted. If the terms allow it, or if title passes to the lender, you may be an unsecured creditor if the lender fails, as Celsius Earn users found in 2023.
What happens to my collateral if the lender goes bankrupt?
It depends on the contract. The Celsius court ruled in January 2023 that Earn deposits worth more than $4.2B belonged to the estate because the terms passed title to Celsius. It left the ownership of Borrow Program collateral undecided.
Are crypto loans safe under MiCA in the EU?
MiCA does not regulate crypto lending and borrowing, and ESMA confirmed in June 2026 that MiCA safeguarding does not cover assets used in lending. National law applies instead.
Cite this page
You are welcome to quote this entry and reuse its pictures with a link to this page.
Vovchyk, S. (2026, November 7). Crypto loans. capyrate Wiki. https://capyrate.com/wiki/crypto-loans<a href="https://capyrate.com/wiki/crypto-loans">Crypto loans, capyrate Wiki</a>